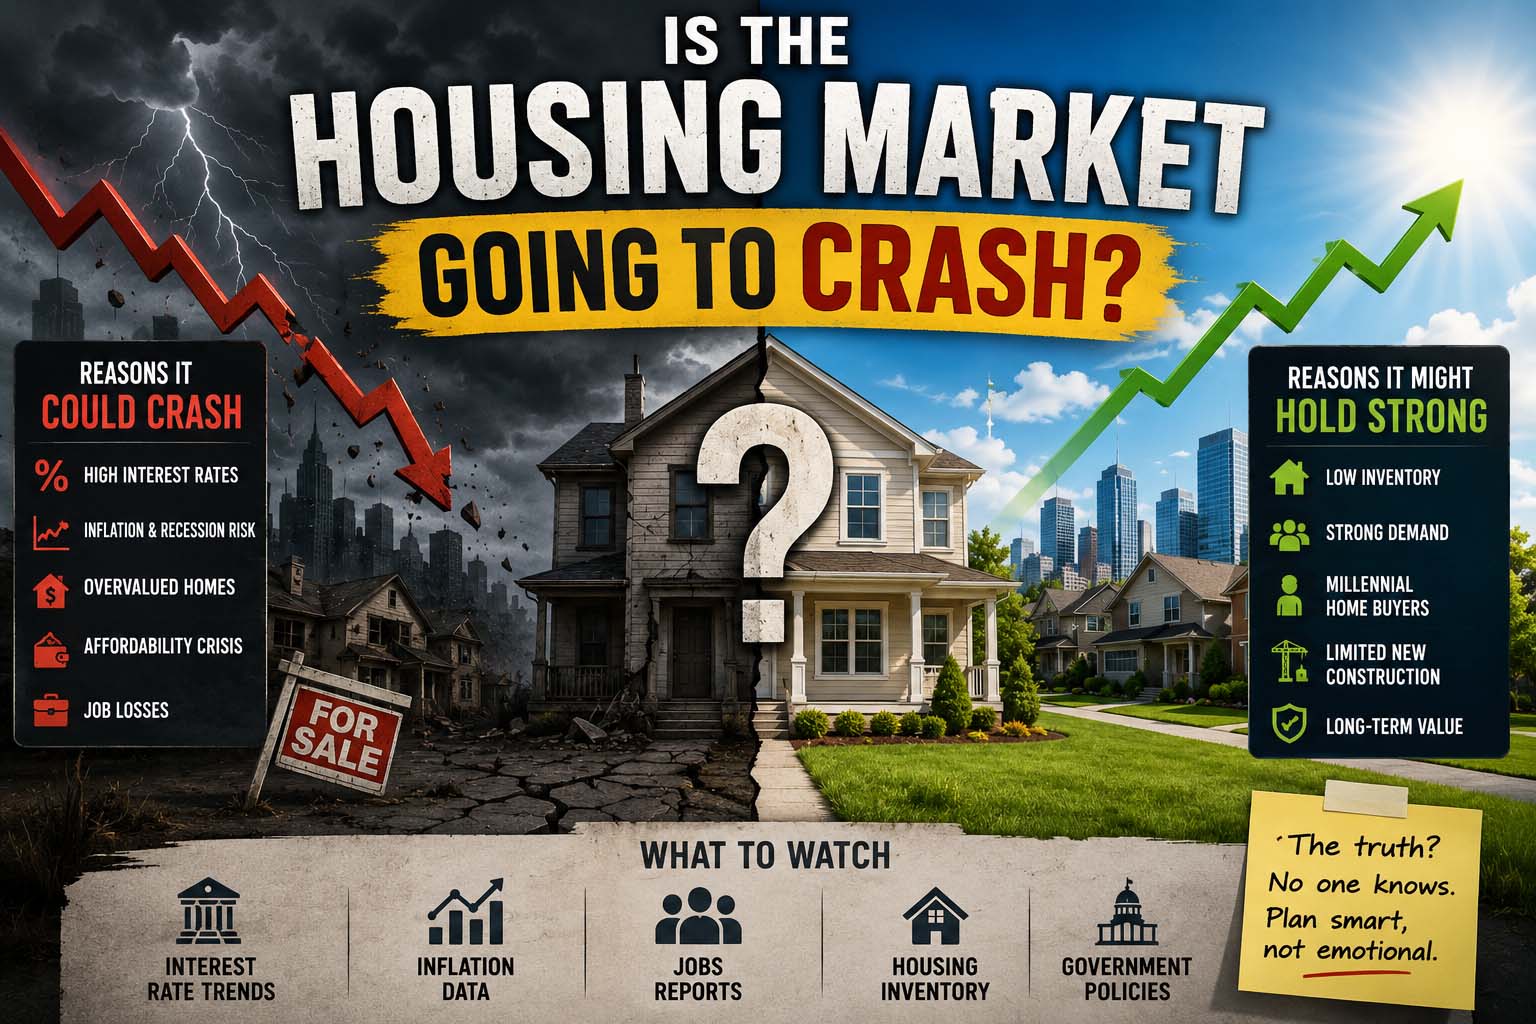
Is the Housing Market Going to Crash? Business and Real Estate Outlook for 2026
The question is the housing market going to crash continues to attract attention as buyers, homeowners, investors, and businesses try to understand what could happen to real estate in 2026. Rising home prices, mortgage rates, inflation, affordability concerns, and economic uncertainty have all contributed to fears of a major downturn.
However, current national forecasts do not point to a broad U.S. housing collapse as the central expectation. Fannie Mae’s Q3 2026 Home Price Expectations Survey shows panelists expecting national home-price growth of 2.5% in 2026 and 2.2% in 2027.
Therefore, buyers should separate national forecasts from local conditions. A slowing market, weaker sales, or falling prices in one city does not necessarily mean the entire U.S. housing market is crashing.
Why People Think the Housing Market Could Crash
Several economic pressures explain why concerns about a housing downturn remain common.
Rising Home Prices and Housing Affordability
Home prices rose substantially in many markets over previous years. As a result, affordability remains difficult for households whose incomes have not kept pace with housing costs.
High prices can also reduce the number of buyers who qualify for suitable homes. However, poor affordability alone does not automatically cause a housing crash.
Higher Mortgage Rates and Housing Demand
Mortgage rates remain an important factor because they directly affect monthly payments. When borrowing becomes more expensive, some buyers reduce their budgets or postpone a purchase.
Consequently, higher rates can weaken housing demand even when home prices remain relatively stable.
Inflation and Economic Pressure
Inflation can reduce household purchasing power because families must spend more on everyday expenses. Therefore, saving for a down payment or managing a new mortgage may become more difficult.
At the same time, inflation and monetary policy can influence borrowing costs and broader economic conditions.
Slower Homebuyer Demand
High prices and borrowing costs can cause potential buyers to wait. As a result, homes may stay on the market longer, and sellers may face less competition.
Still, slower demand should not automatically be interpreted as a crash.
Is the Housing Market Going to Crash in 2026?
Current national forecasts do not identify a 2008-style nationwide collapse as the central scenario.
Fannie Mae’s Q3 2026 Home Price Expectations Survey reports average panel expectations for national home-price growth of 2.5% in 2026 and 2.2% in 2027. These figures indicate expectations for continued price growth at a slower pace rather than a broad national decline.
Fannie Mae’s Home Price Expectations Survey provides the latest panel expectations and related housing research.
However, national averages can hide substantial differences between local markets. Some areas may experience falling prices while others continue to appreciate.
Local housing performance can depend on:
- Employment growth
- Population changes
- Mortgage rates
- Housing inventory
- New construction
- Household income
- Local affordability
- Regional economic conditions
Therefore, homeowners and buyers should pay close attention to their local market instead of relying solely on national headlines.
Housing Market Crash vs. Market Correction
A housing market correction and a housing crash are not the same thing.
A correction generally involves moderate price declines or a period in which prices stop rising rapidly. In contrast, a severe housing crash usually involves broader financial stress, sharp price declines, forced selling, and significant weakness across housing and credit markets.
For example, a city where prices fall after several years of unusually rapid appreciation may simply be experiencing a local correction.
Therefore, declining prices alone do not prove that a nationwide housing crash has started.
What Happened to the Housing Market in 2025?
Concerns about a possible housing downturn were already widespread during 2025. However, housing conditions did not develop into a uniform national collapse.
Instead, high borrowing costs and affordability pressures constrained activity in many parts of the market. Conditions also varied substantially between regions.
This provides an important lesson for 2026: a slow housing market can continue for an extended period without developing into a major financial crisis.
2008 Housing Crash vs. the 2026 Housing Market
Many people naturally compare current conditions with the 2008 housing crisis. However, the circumstances are not identical.
| Factor | 2008 Housing Crisis | 2026 Housing Market |
|---|---|---|
| Lending environment | Major weaknesses were exposed | Lending conditions have a different risk profile |
| Mortgage risk | Significant risky lending contributed to the crisis | Mortgage credit conditions differ from the pre-2008 environment |
| Housing supply | Oversupply affected many markets | Supply conditions vary widely by region |
| Foreclosures | Foreclosures became a major source of market stress | Conditions are not directly comparable with the 2008 crisis |
| Financial system | Severe banking and credit stress | Regulatory and capital conditions differ from that period |
This comparison does not mean housing prices cannot fall. Instead, it shows why analysts should examine the causes of a potential downturn rather than assume that every period of high prices will repeat the events of 2008.
Signs the Housing Market Could Be Heading for a Crash
Predicting exactly when a housing crash will happen is extremely difficult. Nevertheless, several warning signs can indicate increasing stress.
Sharp Rise in Unemployment
Employment provides households with the income needed to make mortgage payments. Therefore, a large and sustained increase in unemployment can weaken housing demand and increase financial stress among homeowners.
Rapid Growth in Foreclosures
A significant increase in distressed homeowners can add forced-sale inventory to the market. Consequently, widespread foreclosure growth deserves attention when evaluating housing crash risk.
Major Housing Oversupply
Housing prices can come under pressure when the number of available properties substantially exceeds buyer demand.
However, inventory conditions vary widely between cities. Therefore, local housing supply data often matters more than broad national assumptions.
Serious Mortgage and Credit Problems
Housing depends heavily on access to mortgage credit. If lending markets experience major disruption, fewer households may qualify for financing.
As a result, severe credit stress can amplify an existing housing downturn.
Falling Consumer Confidence
Consumers may delay major purchases when they worry about employment, income, or the economy. Therefore, prolonged economic uncertainty can weaken housing activity.
How Local Housing Markets Can Perform Differently
Real estate is highly local. Consequently, two cities can experience very different housing conditions during the same national economic environment.
Fast-Growing Housing Markets
Cities with expanding employment and population can maintain housing demand even when national sales slow.
However, affordability can still become a problem if prices rise much faster than local incomes.
Previously Overheated Housing Markets
Markets that experienced rapid price appreciation may face stronger corrections if demand weakens.
Therefore, buyers should compare current prices with local income, inventory, employment, and recent sales trends.
Rural and Smaller Housing Markets
Smaller housing markets can follow different patterns because their supply, employment, and population trends differ from major metropolitan areas.
As a result, national housing statistics may provide limited insight into a specific small community.
How a Housing Market Crash or Downturn Affects Businesses
Housing influences far more than homeowners. In fact, changes in residential real estate can affect construction, finance, retail, professional services, and local economies.
Construction Industry
Slower demand for new homes can reduce construction activity. Consequently, builders, contractors, suppliers, and related businesses may experience weaker demand.
Mortgage and Brokerage Businesses
Banks and lenders can experience lower purchase mortgage volumes when affordability weakens. Meanwhile, brokers and other intermediaries may also see transaction activity change.
For readers unfamiliar with these roles, What Is a Broker explains how professionals may connect buyers, sellers, borrowers, and lenders.
Retail and Furniture Companies
Home purchases often lead to spending on furniture, appliances, repairs, and renovations. Therefore, lower transaction volumes can affect businesses connected to household moves and property improvements.
Local Economies
Housing construction and property activity influence employment, development, and local business demand. As a result, prolonged housing weakness can spread into other parts of a regional economy.
Homebuyer Strategy During Housing Market Uncertainty
First-time buyers often feel pressure to predict exactly what the market will do next. However, personal financial readiness usually deserves more attention than dramatic headlines.
Step 1: Review Your Homebuying Budget
First, calculate the complete cost of homeownership rather than focusing only on the purchase price.
Consider mortgage payments, taxes, insurance, maintenance, and other recurring costs.
Step 2: Review Your Credit
Strong credit can improve a buyer’s access to competitive financing. Therefore, check your credit profile before beginning a serious home search.
Step 3: Research Your Local Housing Market
National trends provide context, but they may not describe your city.
For example, review local inventory, recent comparable sales, time on market, employment conditions, and price changes.
Step 4: Compare Mortgage Options
Interest rates and loan terms can significantly affect long-term affordability. Therefore, compare the complete costs of suitable mortgage options rather than focusing only on the advertised rate.
Step 5: Avoid Emotional Homebuying
Fear of missing out can encourage buyers to overpay. On the other hand, fear of a housing crash can cause financially prepared buyers to wait indefinitely.
The guide What Are Two Questions That Smart Spenders Ask Before Making a Purchase offers a related framework for considering necessity and long-term value before a major purchase.
Business Strategy During Housing Market Uncertainty
Companies connected to real estate should prepare for multiple market scenarios rather than assuming prices will only rise or collapse.
Focus on Long-Term Value
Businesses can prioritize sustainable demand, manageable costs, and healthy cash flow. As a result, they become less dependent on short-term housing market movements.
Diversify Investments
Concentrating too much capital in one asset or market can increase risk. Therefore, investors should consider their overall risk exposure when making decisions.
Watch Mortgage and Interest Rates
Mortgage rates influence affordability and housing activity. Meanwhile, broader interest rates can affect business financing and investment decisions.
Study Local Housing Demand
Some regions can remain competitive while others weaken. Consequently, businesses should monitor the markets where they actually operate.
A Business Strategy Consultant may also help companies assess market changes and develop longer-term plans.
Will Housing Prices Drop in 2026?
Housing prices can decline in individual markets even when national prices rise.
Current national expert forecasts point toward modest price growth rather than a broad housing collapse. However, areas with weaker employment, declining populations, rapidly increasing inventory, or severe affordability problems may perform differently.
Therefore, buyers should avoid interpreting a national housing forecast as a guarantee for every city.
The concept of Cross Price Elasticity also provides useful background on how changes in prices can influence demand relationships between different products and markets.
How Mortgage Rates Affect the Housing Market
Mortgage rates strongly influence how much buyers can afford.
When rates rise, monthly payments increase for the same loan amount. Therefore, some buyers reduce their target price, delay purchasing, or leave the market.
As housing demand cools, sellers may receive fewer offers. In some markets, this can slow price growth or put downward pressure on prices.
However, mortgage rates represent only one part of the housing market. Employment, supply, household formation, incomes, and local demand also influence prices.
Housing Supply, Inventory, and Crash Risk
Inventory remains one of the most important indicators to monitor when evaluating housing market risk.
When very few homes are available, buyers compete for limited supply. In contrast, rapidly increasing inventory gives buyers more choices and can weaken sellers’ pricing power.
However, housing supply conditions vary considerably by region.
Therefore, anyone asking whether a crash is coming should examine both national inventory trends and local listings.
Should Buyers Wait for a Housing Market Crash?
Waiting specifically for a major housing crash involves considerable uncertainty because nobody can reliably identify the exact timing, size, or location of future price declines.
Instead, buyers can focus on factors they control:
- Stable income
- Emergency savings
- Affordable monthly payments
- Suitable financing
- Expected length of ownership
- Local housing conditions
- Personal and family needs
Waiting may make sense when a home would stretch the budget too far. However, financially prepared buyers should not assume that a nationwide crash will automatically produce cheaper overall homeownership.
For those evaluating commercial real estate as well, What Is a Triple Net Lease explains a common commercial property arrangement.
Frequently Asked Questions About a Housing Market Crash
Is the Housing Market Going to Crash?
Current national forecasts do not indicate that a major nationwide U.S. housing crash is the central expectation for 2026. Instead, current expert forecasts point toward modest national price growth, while individual markets may experience corrections.
Could Home Prices Fall Without a Housing Crash?
Yes. Local home prices can decline without creating a nationwide housing crisis. For example, rising inventory, weaker employment, or reduced population growth can put pressure on prices in a specific region.
What Are the Biggest Housing Crash Warning Signs?
A combination of rapidly rising unemployment, widespread mortgage distress, increasing foreclosures, excessive housing supply, and severe credit-market problems would create greater concern.
However, analysts should examine these indicators together rather than treating one weak statistic as proof of an approaching crash.
Should First-Time Homebuyers Wait?
The answer depends on financial readiness, local conditions, affordability, and long-term plans. Therefore, first-time buyers should evaluate their own finances instead of making decisions solely from national housing crash predictions.
Can Anyone Predict When the Housing Market Will Crash?
No reliable method can identify the exact timing of a future housing crash. Economic conditions, employment, interest rates, lending, supply, and buyer behavior can change.
Therefore, forecasts should guide scenario planning rather than serve as guarantees.
Housing Market Outlook for 2026
The 2026 housing market outlook depends on several connected factors, including mortgage rates, employment, inventory, affordability, and regional demand.
A nationwide crash is only one possible scenario. In contrast, individual markets can experience slower sales, flat prices, modest appreciation, or local corrections without creating a national housing crisis.
Therefore, buyers and investors should monitor several indicators together instead of treating one statistic as proof that a crash has started.
Conclusion
The question is the housing market going to crash remains relevant in 2026 because affordability, mortgage rates, inflation, and economic uncertainty continue to influence buyers and investors.
Current national forecasts point more toward modest price growth and regional differences than a 2008-style nationwide collapse. However, that does not mean every local housing market will remain strong.
Therefore, buyers, homeowners, and businesses should monitor employment, mortgage rates, housing inventory, credit conditions, and local demand. More importantly, major financial decisions should depend on personal affordability and local market fundamentals rather than predictions of an exact crash date.