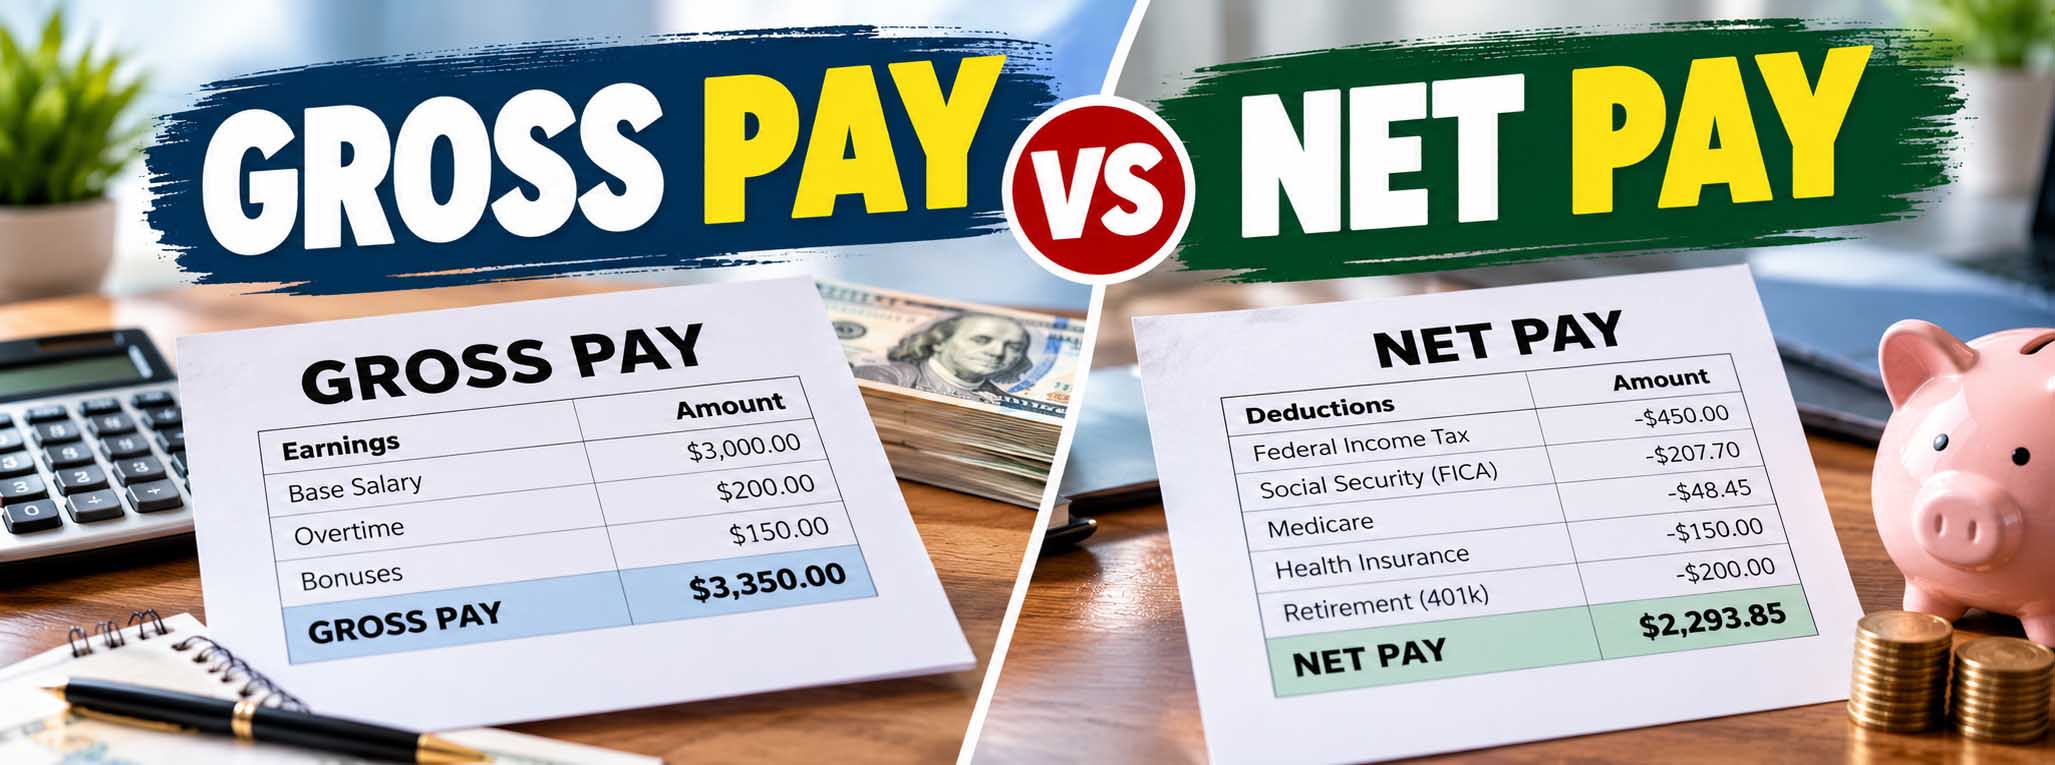
Gross Pay vs Net Pay: Key Differences, Calculations, and Examples
When reviewing a paycheck or preparing a business payroll budget, understanding gross pay vs net pay is essential. Gross pay is the total amount an employee earns before deductions, while net pay is the amount remaining after applicable taxes and other payroll deductions.
For example, an employee earning $4,000 per month might receive only $3,200 in their bank account. The difference comes from deductions such as income tax withholding, Social Security, Medicare, and employee benefit contributions.
Although these two figures appear on the same paycheck, they serve different purposes. Employers use gross earnings to calculate compensation and payroll obligations, while employees rely on net earnings to manage everyday expenses.
This guide explains how both amounts work, why they differ, and how to calculate them using practical examples.
What Is the Difference Between Gross Pay and Net Pay?
The main difference is simple: gross pay represents earnings before deductions, whereas net pay represents the money an employee actually receives after deductions.
However, understanding how those deductions work is useful for both employees and business owners.
Gross Pay Meaning
Gross pay is an employee’s total compensation for a specific pay period before payroll deductions.
Depending on the employee’s compensation arrangement, it may include:
- Regular wages or salary
- Overtime earnings
- Bonuses
- Commissions
- Certain other taxable compensation
For example, an hourly employee who works 40 hours at $25 per hour earns $1,000 in regular gross wages.
If that employee also earns $150 in overtime pay, total gross earnings become $1,150.
However, not every employer-provided benefit counts as cash gross wages, and payroll tax treatment can differ by benefit.
Net Pay Meaning
Net pay is the amount an employee receives after the employer subtracts applicable deductions from gross earnings.
These deductions may include federal income tax withholding, state or local taxes, Social Security, Medicare, retirement contributions, and insurance premiums.
Consequently, net pay is often called take-home pay.
For example, if gross earnings total $1,500 and payroll deductions equal $350, the employee receives $1,150.
Gross Pay vs Net Pay: Quick Comparison
Although the terms are closely related, they answer different financial questions.
| Feature | Gross Pay | Net Pay |
|---|---|---|
| Meaning | Earnings before deductions | Earnings after deductions |
| Also called | Gross earnings | Take-home pay |
| Includes payroll deductions? | Before subtraction | After subtraction |
| Used for | Compensation and payroll calculations | Personal budgeting |
| Usually higher? | Yes | Usually lower |
| Appears on pay stub? | Yes | Yes |
For most employees, gross pay is higher than net pay because taxes and other deductions reduce the final payment.
However, the difference varies according to earnings, withholding information, benefits, and applicable tax rules.
How Gross Pay Is Calculated
The calculation depends on whether an employee receives a fixed salary or earns hourly wages.
Therefore, employers should identify the compensation arrangement before processing payroll.
Gross Pay for Salaried Employees
Salaried employees generally receive a fixed amount of compensation over an agreed period.
For example, suppose an employee earns an annual salary of $60,000.
Their gross pay can be calculated as follows:
Monthly gross pay:
$60,000 ÷ 12 = $5,000
Biweekly gross pay:
$60,000 ÷ 26 = $2,307.69
However, these calculations assume equal salary payments and exclude bonuses or other adjustments.
Gross Pay for Hourly Employees
Hourly gross pay depends on the number of hours worked and the applicable hourly rate.
The basic formula is:
Gross Pay = Hours Worked × Hourly Rate
For example, an employee works 35 hours at $20 per hour.
Their gross earnings are:
35 × $20 = $700
However, overtime must be calculated separately when applicable.
Under federal law, covered nonexempt employees generally receive at least 1.5 times their regular rate for hours worked beyond 40 in a workweek.
State laws or employment agreements may provide greater protections.
Does Employment Status Affect Gross Pay?
Full-time and part-time employees may receive different schedules, benefits, or compensation arrangements.
However, gross pay still represents earnings before deductions.
For employers comparing the difference between part time and full time, understanding scheduled hours and benefits eligibility can help explain differences in payroll costs.
How to Calculate Net Pay Step by Step
Once gross earnings are established, employers subtract the deductions that apply to the employee.
This calculation is a central part of payroll administration.
For business owners asking what is payroll, the process includes calculating employee compensation, withholding required amounts, and distributing wages accurately.
Step 1: Determine Gross Earnings
Start with the employee’s total wages for the pay period.
For example, assume an employee earns $4,000 per month before deductions.
Step 2: Identify Applicable Payroll Taxes
Next, calculate the required tax withholding.
In the United States, common payroll taxes include:
- Federal income tax withholding
- State income tax withholding, where applicable
- Local income taxes, where applicable
- Social Security tax
- Medicare tax
For most employees, the standard Social Security withholding rate is 6.2% on wages up to the annual wage base.
Meanwhile, the standard Medicare withholding rate is 1.45%, with Additional Medicare Tax potentially applying to higher earnings.
However, income tax withholding depends on individual circumstances and applicable tax rules.
The Internal Revenue Service’s employment tax guidance explains federal employer responsibilities for income tax withholding, Social Security, Medicare, and other employment taxes.
Step 3: Subtract Employee Benefit Contributions
Some employees contribute toward health insurance, retirement plans, or other workplace benefits.
For example, an employee might contribute $200 toward health insurance and $150 toward retirement savings.
However, some contributions are deducted before certain taxes are calculated, while others are deducted afterward.
Therefore, payroll calculations must follow the correct tax treatment rather than simply subtracting every item in the same order.
Step 4: Calculate the Final Take-Home Amount
After determining the applicable taxes and deductions, calculate the remaining payment.
The simplified formula is:
Net Pay = Gross Pay − Total Payroll Deductions
For example:
$4,000 − $800 = $3,200
Therefore, the employee receives $3,200 in net pay.
Gross vs Net Pay: Real-World Paycheck Example
Consider a small business employee earning $5,000 in gross wages during a monthly pay period.
The employer calculates the following illustrative deductions.
| Paycheck Item | Amount |
|---|---|
| Gross monthly pay | $5,000 |
| Federal income tax withholding | $450 |
| State income tax withholding | $150 |
| Social Security tax | $310 |
| Medicare tax | $72.50 |
| Health insurance contribution | $200 |
| Retirement contribution | $250 |
| Total deductions | $1,432.50 |
| Net monthly pay | $3,567.50 |
In this simplified example, the employee earns $5,000 but receives $3,567.50.
However, the amounts are illustrative rather than a personalized tax calculation.
Actual withholding depends on the employee’s tax information, jurisdiction, benefit arrangements, and whether deductions receive special tax treatment.
What Deductions Reduce Take-Home Pay?
Not every employee has the same deductions.
As a result, two workers earning identical gross wages may receive different net payments.
Mandatory Payroll Deductions
Employers generally must withhold applicable taxes and comply with legally required deductions.
For example, federal income tax withholding depends partly on the employee’s Form W-4 and payroll calculations.
Likewise, court-ordered wage garnishments may apply in certain circumstances.
However, employers must follow applicable legal limits and procedures.
Voluntary Payroll Deductions
Employees may also authorize deductions for workplace benefits.
Common examples include retirement contributions, health insurance premiums, and certain other benefit programs.
However, the tax treatment of these contributions varies.
For instance, traditional pretax retirement contributions generally reduce federal taxable income but usually do not reduce Social Security or Medicare wages.
Consequently, accurate payroll records are necessary to calculate net earnings correctly.
Why Gross Pay vs Net Pay Matters for Businesses
Understanding employee compensation helps employers manage payroll expenses, prepare budgets, and communicate clearly with staff.
However, gross wages are only one part of the employer’s total labor cost.
Managing Payroll Expenses
Businesses must consider employee wages alongside employer payroll taxes, insurance, and benefit expenses.
For example, a company paying $50,000 in annual gross salary may spend more than $50,000 when employer-side obligations and benefits are included.
Therefore, using employee take-home pay to estimate business labor costs would produce an inaccurate budget.
Processing Employee Payments Correctly
Accurate payroll requires reliable time records, compensation information, tax withholding, and benefit deductions.
For small business owners learning how to process payroll, checking each component before payday can reduce errors and employee confusion.
Meanwhile, clear pay statements help workers understand how their earnings were calculated.
Improving Employee Communication
Employees sometimes compare their job offer with the amount deposited into their bank accounts.
However, an advertised salary normally refers to gross compensation unless stated otherwise.
Therefore, employers should explain the distinction during onboarding and provide accessible information about payroll deductions.
Net Pay vs Gross Pay for Personal Budgeting
Employees should generally use expected net earnings when planning everyday spending.
For example, someone earning $4,500 in monthly gross pay may have substantially less available after taxes and benefit contributions.
Consequently, budgeting with the full gross amount could create unrealistic spending expectations.
Planning Monthly Expenses
Start with the amount typically deposited into your account.
Next, allocate money toward housing, utilities, transportation, groceries, savings, and other expenses.
However, employees with variable hours or commissions should consider using a conservative income estimate.
This approach can make financial planning more predictable.
Comparing Job Offers
Suppose one employer offers a higher gross salary but requires larger employee insurance contributions.
Meanwhile, another employer offers slightly lower wages with more affordable benefits.
Although the first salary appears more attractive, comparing estimated take-home pay and total benefits provides a clearer picture.
Therefore, evaluate compensation packages rather than focusing only on the advertised salary.
Common Payroll Mistakes to Avoid
Even experienced businesses can encounter problems when calculating employee earnings.
However, regular payroll reviews can help prevent many avoidable errors.
Common mistakes include:
- Confusing gross wages with take-home pay. Always distinguish compensation before and after deductions.
- Calculating overtime incorrectly. Follow applicable wage and hour laws.
- Using outdated withholding information. Review employee records and current tax requirements.
- Treating every deduction identically. Pretax and after-tax contributions may affect calculations differently.
- Ignoring employer payroll expenses. Include employer-side taxes and benefits in labor budgets.
- Failing to review pay statements. Check unusual changes before payments are finalized.
For growing businesses, understanding why outsource payroll may also help determine whether external payroll support is appropriate.
However, outsourcing does not automatically eliminate the employer’s responsibility for payroll compliance.
Frequently Asked Questions About Gross and Net Pay
Is Gross Pay the Same as Salary?
Not always. Salary describes an employee’s agreed compensation arrangement, while gross pay represents earnings for a particular period before deductions.
For example, gross pay may include bonuses or other compensation beyond base salary.
Is Net Pay the Amount Deposited Into Your Bank Account?
Usually, yes. Net pay generally represents the amount available for payment after applicable payroll deductions.
However, the employee may receive that amount through direct deposit, a paycheck, or another permitted payment method.
Why Is My Net Pay Lower Than My Gross Pay?
Taxes, insurance contributions, retirement deductions, and other applicable withholding amounts reduce take-home earnings.
Therefore, the difference depends on the deductions associated with your paycheck.
Can Two Employees Have the Same Gross Pay but Different Net Pay?
Yes. Employees may have different tax withholding elections, benefit contributions, or other deductions.
Consequently, identical gross wages do not always produce identical take-home payments.
Which Amount Should Businesses Use When Calculating Labor Costs?
Businesses should start with gross wages and include applicable employer payroll taxes, benefits, and other employment expenses.
However, employee net pay alone does not represent the employer’s total labor cost.
Is Gross Pay Before or After Taxes?
Gross pay is generally calculated before payroll taxes and employee deductions.
Meanwhile, net pay reflects the remaining amount after those deductions.
Making Better Payroll and Compensation Decisions
Understanding the difference between gross and net earnings helps employees interpret paychecks and allows businesses to manage compensation more accurately.
For employees, gross pay shows earnings before deductions, while net pay provides a more realistic figure for everyday budgeting.
For employers, accurate calculations support reliable payroll processing, clearer communication, and better financial planning.
Whether you’re reviewing a job offer or managing employee wages, start by identifying gross earnings, checking applicable deductions, and confirming the final payment.
By reviewing these figures regularly, both employees and business owners can make more informed financial decisions.